Showing posts with label denver hot market. Show all posts

Monday, June 13, 2016

Baby Boomers Heading 
Back to the City


Unlike previous generations, many baby boomers aren't planning their retirement in sunny southern locales. Instead, more are choosing to move back to metro areas they had left when they started raising a family in the suburbs.

Baby boomers, those born between 1946 and 1964, are the largest and wealthiest generation to ever retire and they're making their imprint and redefining urban centers.

About 11 percent of home buyers aged 50 to 59 closed on homes in urban areas and central cities from July 2013 through June 2014, according to a 2015 report by the National Association of REALTORS®. However, that percentage is rising, up to 13 percent this year. Baby boomers are estimated at 74.9 million people so even the slightest percentage jump equates to a dramatic shift.

Some of the most walkable urban centers and college towns are seeing some of the highest growth from baby boomers moving in, says Jonathan Smoke, realtor.com®'s chief economist. They tend to be drawn to the condos, nearby restaurants and shops, cultural venues, as well as places where they can take classes and workshops.

New buildings are offering amenities to cater to this demographic, such as concierge services similar to hotels that help them with everything from dog walking to planning parties. Builders are also constructing more urban two-bedroom residences with dens and expanded laundry rooms (that can also be repurposed as hobby, craft centers, or miniature offices), says Isabell Kerins, a director of product and business development at John Burns Real Estate Consulting.

Also, more high-end dining boutiques, art galleries, theaters, and cultural organizations are moving in to downtowns to appeal to boomers' who may have more leisure time and more money to spend than younger residents, says Harris Steinberg, executive director of the Lindy Institute for Urban Innovation at Drexel University.

Developers also are creating more "urban suburbs" to appeal to boomers who want the urban lifestyle but don't want to move into the city core. For example, some builders are looking to create walkable areas in suburbs with condos near restaurants and retail to appeal to baby boomers urban desires.

Source: RealtorMag
Mortgage Rates Slightly Up,
Buyers are Still Coming


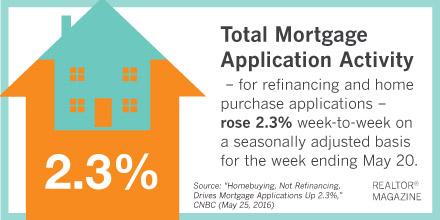
Mortgage rates may have inched up slightly but that didn't seem to deter home buyers from shopping for a loan last week. Mortgage application volume rose 2.3 percent week-over-week on a seasonally adjusted basis, driven by an uptick in home purchase applications, the Mortgage Bankers Association reports. Mortgage applications are nearly 24 percent higher than they were a year ago.

After a short dip, mortgage applications for home purchases reversed course last week and rose 5 percent. Purchase applications are 17 percent higher than a year ago.

"Purchase applications got back on track last week, resuming the level of activity observed throughout most of April and May," says Lynn Fisher, MBA vice president of research and economics. MBA also reported that the average loan size for purchase applications rose to a survey high last week, reaching $307,700.

Meanwhile, applications for refinancing mostly held flat last week, budging just 0.4 percent during the week. MBA reports the average on a 30-year fixed-rate mortgage rose to 3.85 percent last week, up from 3.82 percent the prior week.


Source: RealtorMag
Denver Ranked as
Best Tech Hot Spot


Denver was named as the best city for tech professionals based on wages and home prices, according to Homes.com’s New Tech City Index. The rankings looked at 365 cities, factoring in the average wage in the sector, industry employment in the city, and the average house price for employees moving there.

Denver tech professionals boast an average wage of $91,861, and the city has seen explosive growth in its housing market in the past five years, with prices up 41 percent in the past five years.


“Many areas exist outside of the Bay Area and the Pacific Northwest where tech folks can find both their dream job and the home of their dreams,” says Grant Simmons, vice president at Homes.com. “Cities like Denver not only offer great tech-focused career opportunities, but also more bang for their housing buck, great schools, and lifestyle options that suit both small-town and big-city appetites.”


The index singled out Columbus, Ohio as the most affordable place for tech workers to live. The average home price there is $107,367. On the other hand, Oakland, Calif., saw the biggest growth in home prices among emerging tech hub areas, with prices growing nearly 48 percent in the past five years.


Here are the top 20 cites for tech professionals, according to the index:
  1. Denver
  2. Framingham, Mass.
  3. Oakland, Calif.
  4. Atlanta
  5. Boston
  6. Austin, Texas
  7. Santa Ana, Calif.
  8. Baltimore, Md.
  9. Durham, N.C.
  10. Boulder, Colo.
  11. Columbus, Ohio
  12. Trenton, N.J.
  13. Newark, N.J.
  14. Bridgeport, Conn.
  15. Minneapolis
  16. Huntsville, Ala.
  17. Charlotte, N.C.
  18. Raleigh, N.C.
  19. Bethesda, Md.
  20. Wilmington, Del.
Source: RealtorMag

Friday, April 20, 2012

Denver #2 Hottest Market in U.S.

DENVER (CBS4)- Denver may be the exception to the downturn in the real estate market. A recent report puts the Mile High City at number two in the nation for the short length of time a house stays on the market.
The news is good for sellers but buyers can find the quick turnaround frustrating.
Homeowner Holly Wilcher sold her home in less than a month.
“We had an offer in seven days,” said Wilcher.
She received three offers on her house, all of which were more than what she paid for it a year ago.
That’s great news for sellers but buyers say there’s no time to wait if they find a house they like.

“My real estate called their agent and he said they already had an offer so I had to put in an offer really fast and make in an aggressive offer because that would be contingent upon the other offer,” said potential home buyer Josh, who didn’t want to give his last name.
Scott Peterson is a real estate agent and hasn’t seen the market this tight since before the housing bubble burst.
“I’ve been in real estate for six years and I’ve never seen anything like it,” said Peterson. “The lack of inventory and large demand is really what’s driving up prices.”
Many of his recent listings have sold in two to seven days. The price range selling well can fit into a variety of income levels.
“I’ve got listings anywhere from $250,000 all the way up to $625,000.”
“If there’s something you like you’ve got to jump on it.”

Advice For Buyers:
  • Stalk the neighborhood real estate and drive through daily.
  • Work with an agent who is intimately familiar with the neighborhood where you want to buy.
  • If the house you like is better than others you’ve seen, consider making a full-price offer or even slightly above.
  • Have your real estate agent call the listing agent to learn more about competition from other buyers.
Advice For Sellers:
  • If you’re considering selling, list it immediately.
  • Price it on the higher end but don’t get greedy.
  • Work with an agent who knows and sells in your neighborhood.
  • Know your competition and make the presentation of your home better.

(I told you!  -Jonathan)